Serious physical injuries after a collision create immediate chaos for victims trying to reconstruct their daily routines. Medical bills accumulate quickly while lost wages strain household budgets to extreme limits.
Navigating claims through aggressive insurance adjusters presents another layer of heavy stress during recovery. Securing proper guidance helps individuals pursue fair compensation without accepting unfair initial settlements.
Understanding The True Value Of Injuries
Insurance companies frequently calculate early payout offers based on minimal immediate medical expenses. These early calculations routinely ignore long-term rehabilitation demands, specialized therapies, and ongoing prescriptions needed for complete physical recovery. Victims often rush into accepting low figures before realizing full diagnostic outcomes.
Calculating future financial needs requires thorough documentation from medical experts and economic analysts. Partnering with a skilled personal injury attorney helps claimants quantify every single loss associated with their traumatic event. Legal professionals analyze past case outcomes to establish realistic compensation ranges for non-economic damages like pain and suffering.
Adjusters work to minimize company payouts by downplaying soft tissue damage or pre-existing physical conditions. Comprehensive medical evaluations counter these defensive tactics by connecting explicit bodily harm directly to the crash. Detailed medical records build an undeniable evidentiary foundation for ongoing negotiations.
Avoiding Early Settlement Pitfalls
Claims representatives typically contact injured parties within days of an incident to offer quick cash resolutions. Accepting these initial proposals revokes all rights to pursue additional financial recovery if future complications emerge. Strategic patience remains a critical asset when establishing the full scope of harm.
Court guidelines highlight that judges actively encourage disputing parties to reach mutual agreements to avoid trial expenses and lengthy delays. This structural preference means settlement discussions form the primary stage where claims get resolved. Careful preparation during early negotiations sets the trajectory for favorable pre-trial outcomes.
Recorded statements given without counsel can easily be weaponized against injury victims later in proceedings. Insurance adjusters ask leading questions designed to shift liability onto the injured party. Declining informal recorded conversations protects the integrity of the pending legal claim.
Gathering Crucial Documentation And Proof
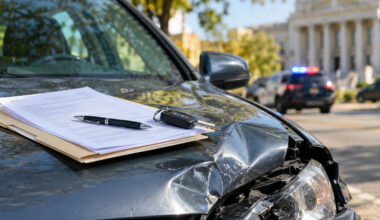
Building a robust case requires systematic collection of every piece of tangible evidence from the collision scene. Photos of vehicle damage, road conditions, traffic signals, and physical injuries provide undeniable visual context. Police reports offer official third-party observations regarding fault and citations issued at the location.
Medical records serve as the central pillar for establishing the severity of bodily harm. Consistent attendance at therapy sessions shows commitment to recovery and proves the legitimate nature of reported pain. Gaps in treatment schedules give defense representatives excuses to challenge claim validity.
Financial documentation must detail every cent lost due to missed work hours or reduced earning capacity. Pay stubs, tax records, and employer statements confirm the exact wage losses tied directly to the injury. Detailed daily journals recording physical pain levels further support claims for emotional distress.
Deciphering Complex Insurance Policy Terms
Insurance policies contain technical language designed to define strict boundaries for coverage amounts. Policyholders frequently struggle to understand clauses regarding underinsured motorist coverage or personal injury protection benefits. Clear interpretation of policy language prevents insurers from hiding behind confusing contractual terms.
Multiple coverage policies sometimes apply to a single accident, creating overlapping sources of recovery. Umbrella policies, commercial coverage, and personal automotive plans may all play distinct roles in fulfilling the total claim amount. Identifying every available policy maximizes potential financial recovery for the victim.
Subrogation rights can complicate final payout disbursements when health insurance companies demand reimbursement. Lien negotiations require careful handling to ensure medical providers do not absorb the entire settlement sum. Resolving outstanding liens guarantees that crash victims keep a fair portion of their recovery.
Negotiating Aggressively With Adjusters
Settlement negotiations usually begin with a formal demand letter outlining liability and total damages suffered. This initial legal document sets high expectations supported by attached medical invoices and economic reports. Adjusters respond with counteroffers that test the claimant’s willingness to hold firm.
Data published by federal court journalists reveals that the vast majority of civil cases conclude prior to trial through judicial orders or negotiated settlements between parties. Understanding this reality gives claimants confidence during aggressive back-and-forth negotiations. Strategic legal leverage forces adjusters to offer realistic numbers rather than risking public courtroom proceedings.
Effective negotiation requires presenting clear risks to the insurance company regarding potential trial costs. Presenting organized evidence early shows adjusters that the claimant is ready to litigate if reasonable terms are not reached. Persistent advocacy remains the primary driver of top-tier financial outcomes.
Managing Long-Term Rehabilitation Costs
Catastrophic injuries demand financial planning that far exceeds immediate emergency room bills. Severe spinal damage, traumatic brain injuries, and complex fractures necessitate ongoing therapy, home modifications, and assistive medical devices. Failure to project these future expenses leaves victims financially vulnerable years after a settlement closes.
Long-term financial assessments must include several key categories of future expenses:
- Ongoing physical therapy and specialized rehabilitation programs.
- In-home caregiving support and necessary structural home modifications.
- Future surgical procedures and replacement medical equipment needs.
Life care planners evaluate medical prognosis reports to forecast exact lifetime costs associated with chronic injuries. These detailed projections prevent claimants from settling for lump sums that exhaust prematurely. Comprehensive future planning guarantees long-term security for injured individuals and their families.
Preparing For Litigation When Negotiations Stall
Negotiations sometimes stall when insurance providers refuse to make fair settlement offers in good faith. Filing a formal lawsuit changes the dynamic of the dispute by placing strict court deadlines on the insurance defense team. Litigation signals complete willingness to present the evidence directly before a jury.
The discovery phase allows both sides to inspect evidence, take depositions, and evaluate witness credibility. Uncovering internal insurance notes or obtaining clear expert witness statements often shifts the balance of power toward the plaintiff. Unfavorable pre-trial discovery outcomes frequently motivate insurers to re-open settlement discussions with higher offers.
Final pre-trial conferences offer a last opportunity to reach consensus under court supervision. Judges routinely guide parties toward a realistic middle ground during these structured settlement discussions. Having strong legal representation ensures injury victims navigate this final high-stakes phase with complete confidence.
Navigating recovery after a severe accident requires managing medical treatments while contesting aggressive insurance settlement tactics. Protecting long-term financial security depends heavily on understanding the true value of every physical and economic loss.
Building an unyielding case through thorough evidence gathering and firm negotiation places claimants in the best position for recovery. Taking proactive legal action guarantees that insurance providers face real accountability while injured parties focus entirely on healing.